

Why Colorado Is the Best State to Buy a Short-Term Rental and Use the STR Tax Loophole
This article is educational and is not tax, legal, or investment advice. Evergreen Escapes is a short-term rental co-hosting company, not a CPA firm. Tax law changes, and your outcome depends entirely on your own facts. Work with a real estate CPA before you buy anything based on what you read here.

There is a well-known escape hatch called Real Estate Professional Status, but it
requires 750 hours a year and more than half your working time in real estate. If you are a busy professional with a demanding career, that door is closed.
The short-term rental exception is the door that stays open.
Buried in the passive activity regulations is a definition point that changes everything. If the average period of customer use of your property is seven days or fewer, the activity is not treated as a rental activity at all for passive loss purposes. It is treated as a trade or business. That means Real Estate Professional Status is not required. You only have to materially participate.
This is why people call it a loophole. It is not aggressive tax positioning. It is a specific carve-out in Treasury regulations that Congress and the IRS have left in place for decades. It just happens to be enormously valuable to the right buyer.
The two conditions you have to meet the short-term rental tax loophole
Everything depends on clearing both of these. Miss either one and the strategy collapses.
1. Average stay of seven days or fewer. This is measured as an average across the tax year, not a maximum. A handful of ten-night stays will not disqualify you if your average lands under seven. But a property loaded with 30-day corporate or snowbird bookings will blow the test.
2. Material participation. You have to meet one of the IRS material participation tests. The three that matter most in practice:
500 hours. You spend 500 or more hours on the activity during the year. No one else's hours matter under this test.
Substantially all. Your participation is essentially all of the participation in the activity.
100 hours and more than anyone else. You spend at least 100 hours, and no other individual spends more than you. This includes your co-host, your cleaners, your handyman, and anyone else.
That third test is where most people get into trouble, and we are going to come back to it in detail, because it is the question every serious buyer asks us.

What changed in 2026: 100% bonus depreciation is back and permanent
For a few years this strategy was getting weaker. Bonus depreciation was phasing down on a schedule: 80% in 2023, 60% in 2024, 40% in 2025, and headed to zero by 2027.
That phase-down is gone. The One Big Beautiful Bill Act, signed in July 2025, permanently restored 100% first-year bonus depreciation for qualifying property acquired after January 19, 2025. The IRS issued interim guidance on the transition in early 2026.
Permanent in tax language means until Congress changes it again, but there is no scheduled sunset on the books. For the first time in years, an investor buying a short-term rental today can front-load the full deduction instead of a fraction of it.
One detail worth confirming with your closing documents: the 100% rate hinges on an acquisition date after January 19, 2025. Property under a written binding contract signed before that date can fall outside the rule.
How the deduction gets big: cost segregation
A residential rental depreciates over 27.5 years. On a $760,000 depreciable basis, that is roughly $27,600 a year. Useful, but not life-changing.
A cost segregation study changes the math. An engineering-based study breaks the property into components and reclassifies everything that is not structural into shorter recovery periods:
5-year property: appliances, furniture, cabinetry, carpet, window treatments, specialty electrical
15-year land improvements: driveways, retaining walls, decks, fencing, landscaping, exterior lighting, septic, propane systems
Those shorter-life components are bonus-eligible. With 100% bonus depreciation, they come off in year one.
An illustrative Colorado example
Say you buy a $950,000 mountain home outside Woodland Park or in Bailey. These figures are illustrative and your actual study will differ.
Line item | Amount |
Purchase price | $950,000 |
Land allocation (est. 20%) | $190,000 |
Depreciable basis | $760,000 |
Reclassified to 5, 7, and 15-year property (est. 27%) | $205,200 |
First-year bonus depreciation on that bucket | $205,200 |
Federal tax reduction at a 37% marginal rate | roughly $75,900 |
That is before the ordinary 27.5-year depreciation on the remaining basis, and before your operating deductions.
Two honest caveats. First, an excess business loss limitation caps how much business loss can offset non-business income in a single year, with the remainder carried forward. Second, accelerated depreciation is subject to recapture on sale unless you exchange into another property. Your CPA will model both.
Why Colorado specifically
Plenty of states have short-term rentals. Very few of them line up this cleanly with the rules.

1. Colorado mountain demand is naturally short-stay
The seven-day average is the condition people fail without realizing it. Markets built on monthly snowbird stays, traveling nurses, or corporate relocations drift right past the threshold.
Colorado mountain travel does not. Ski weekends, summer trailhead trips, Mueller State Park camping alternatives, Garden of the Gods and Pikes Peak sightseeing, elk season, fall color runs. The average booking in our portfolio sits comfortably in the two to four night range. The seven-day test is not something you have to engineer here. It is how the market already behaves.
2. Mountain homes cost-segregate exceptionally well
This is the part most out-of-state investors miss. Colorado mountain properties are loaded with exactly the components that reclassify into 5-year and 15-year buckets.
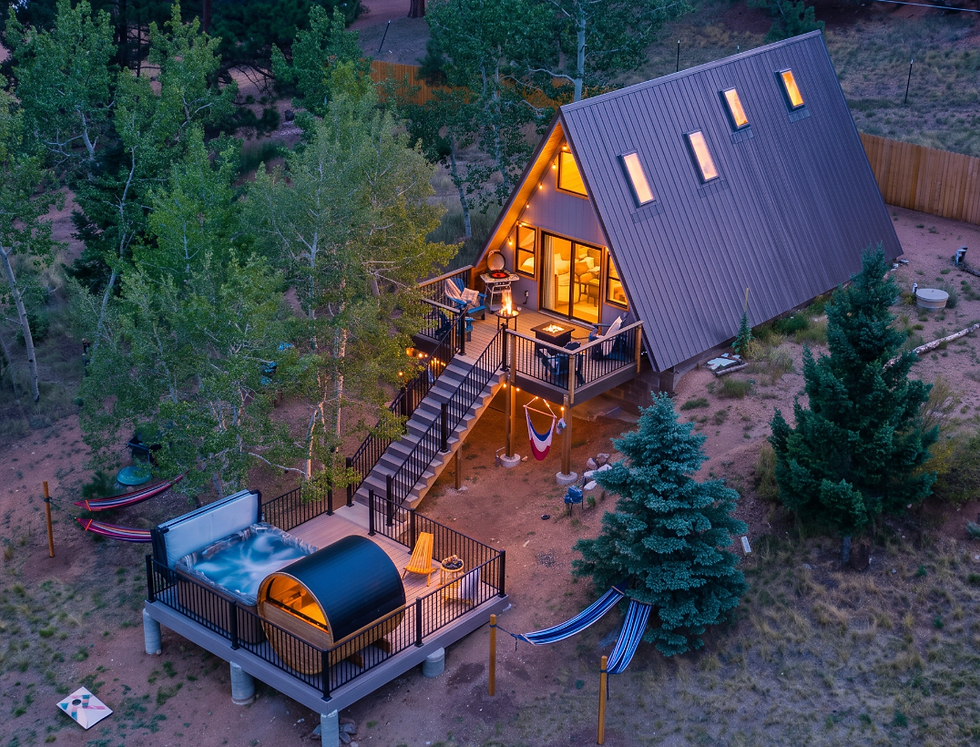
Long gravel or paved driveways. Septic systems and wells. Multi-level decking. Hot tubs and pads. Propane tanks and lines. Retaining walls. Fire mitigation landscaping. Fencing. Detached garages and outbuildings. Exterior lighting.
A suburban tract home in a flat market has almost none of that. A Divide or Bailey cabin has all of it. Two properties at the same purchase price can produce meaningfucost segregation results, and mountain properties consistently land on the favorable side.
3. Property taxes stay low, and the classification threat did not pass
Colorado has among the lowest effective property tax rates in the country. That matters when you are holding a high-basis asset.
There was a serious effort to change this. House Bill 24-1299 would have reclassified non-owner-occupied short-term rentals as lodging property, roughly quadrupling the assessment rate. It was postponed indefinitely in committee in April 2024 and never became law. You will find blog posts online claiming it took effect January 1, 2026. That is incorrect. Colorado short-term rentals remain classified as residential real property.
That is worth knowing before you write off Colorado based on something you read.
4. Colorado's income tax is flat and low
Colorado applies a flat 4.4% rate using federal taxable income as the starting point. Compare that to California at 13.3% or Oregon near 9.9%. The state has decoupled from certain federal provisions, so ask your CPA specifically how your bonus depreciation deduction flows through to your Colorado return, but the baseline environment is favorable.
5. It is a drive-to market, which makes material participation realistic
Material participation is measured in hours. Travel time to and from the property in service of the activity generally counts when the trip's purpose is the business.
Colorado is 60 to 120 minutes from Denver International or Colorado Springs Airport to most of our markets. An owner in Dallas, Chicago, Phoenix, or Denver can be at the property, do a full walkthrough, meet a contractor, handle a turnover, and be back the same day or next morning. That accessibility turns "I will get my hours in" from a hope into a schedule.
6. The regulatory map rewards local knowledge
Colorado does not have statewide short-term rental regulation. It is governed county by county and town by town, and the difference is dramatic.
Breckenridge capped licenses at 2,200, down from 3,945. Manitou Springs holds at 2% of residential structures. Colorado Springs runs a primary residency audit program. Meanwhile Park County adopted a new ordinance in 2026 with no cap on licenses or rental nights, and unincorporated El Paso County has no county permit requirement at all for renting a principal structure.
This is where buying blind gets expensive. The markets we operate in, Woodland Park, Divide, Bailey, Cascade, Green Mountain Falls, Idaho Springs, and Evergreen, were chosen deliberately.
7. Year-round demand means a Q4 purchase still works
To claim depreciation for a tax year, the property must be placed in service, meaning available and ready to rent, before December 31.
In a seasonal beach market, buying in October means a dead property until spring. In the Colorado high country, a home placed in service in November walks straight into ski season, holiday travel, and New Year bookings. You start generating revenue, real participation hours, and a documented operating history immediately. That timing flexibility is a genuine structural advantage.
The question nobody wants to answer: can you use a property manager and still qualify?

This is the part of the strategy where most articles go quiet, and it is the most important part for the buyer we are describing.
The honest answer is that it depends on how you structure it, and that traditional full-service property management is a real risk to the deduction.
If you hand the entire operation to a management company that handles everything, you are almost certainly out on the substantially all test and likely out on the 100 hours and more than anyone else test. The Tax Court has decided cases on exactly this point. In Lucero v. Commissioner, the taxpayers lost because their management company out-participated them. In Mirch v. Commissioner (2025), the court reinforced that the strategy lives and dies on contemporaneous documentation.
So what actually works?
Co-hosting is structurally different from full-service management. In a co-hosting model, the owner stays the operator of record and the decision-maker. We handle execution: listing optimization, dynamic pricing, guest messaging, screening, cleaner coordination, hot tub service, snow removal coordination, and payout. The owner remains responsible for capital decisions, design direction, vendor selection, budget approval, property strategy, and physical presence. BOOK A CALL WITH EVERGREEN ESCAPES
Year one is where owners bank hours. Furnishing and staging. Design decisions. Contractor walkthroughs. Vendor interviews and selection. Amenity installs. Property setup and inventory. Photography direction. Market research and pricing strategy. Travel to and from the property. For an engaged owner, 100 hours in the acquisition and setup year is not a stretch. Many clear it before the first guest arrives.
Documentation is the whole game. Reconstructed logs and rounded estimates do not survive audit. Contemporaneous, dated, specific records do. Log the hour on the day you spend it.
Ask your CPA the specific question before you sign anything. Not "does short-term rental work?" but "given my income, my hours, and a co-hosting arrangement where I stay the operator, which material participation test am I targeting, and what documentation do you want?"
We would rather tell you this up front than have you find out in year two. If your CPA's plan requires you to be the primary participant, we will tell you exactly which hours we log so you can plan around it. That is a conversation we have with owners regularly, and it is one of the reasons investors work with us instead of a traditional management company.
Where we see the best fit in Colorado right now

Bailey and Park County. Under an hour from Denver, a 2026 ordinance with no caps on licenses or nights, and a market that is professionalizing fast.
Woodland Park and Divide, Teller County. Mueller State Park, Pikes Peak, off-roading, and fishing. The county is finalizing its first short-term rental ordinance, so check current rules before you buy.
Idaho Springs and Clear Creek County. I-70 corridor access, hot springs, and strong ski-adjacent demand.
Evergreen and Conifer, Jefferson County. Denver-proximate, high-end inventory, and a new permit pathway adopted in late 2025 that made this market viable again.
Cascade and Green Mountain Falls, El Paso County. Pikes Peak Highway traffic and Colorado Springs proximity, with no county permit requirement in unincorporated areas.
A realistic timeline if you want this for the current tax year
Talk to a real estate CPA and confirm the strategy fits your income and your hours.
Get pre-approved. DSCR financing is common for this buyer profile and does not rely on personal income documentation.
Choose your market and identify a property that actually performs, not just one that photographs well.
Close, furnish, and get the property listed and available to rent before December 31.
Order a cost segregation study.
Log every hour from day one.
Bring in a co-host who understands the tax structure you are operating under.
That last step matters more than most owners realize. The wrong operating partner can quietly cost you the deduction that motivated the purchase in the first place.

Frequently asked questions
Is the short-term rental tax loophole still legal in 2026? Yes. It is a carve-out in the passive activity regulations, not an aggressive position. The 2025 tax act made 100% bonus depreciation permanent for qualifying property acquired after January 19, 2025, which made the strategy stronger, not weaker.
Do I need Real Estate Professional Status? No. That is the entire point of the seven-day exception. You need material participation, not REPS.
Does it matter whether I list on Airbnb, Vrbo, or direct? No. The platform is irrelevant. The average stay length and your participation are what count.
Can I still use the strategy if I hire a co-host? Potentially, but structure and documentation determine the answer. Full-service management where the manager out-participates you is the common failure point. Discuss the specific arrangement with your CPA before closing.
What happens when I sell? Accelerated depreciation is subject to recapture. A 1031 exchange into another property can defer it. Model the exit before you model the entry.
Does Colorado tax short-term rentals as commercial property? No. The bill that would have done that, HB24-1299, was postponed indefinitely in 2024 and never became law. Colorado short-term rentals remain classified as residential real property.
The short version
The tax code rewards a specific combination: a property with short average stays, a heavy load of depreciable components, an owner who stays genuinely involved, and clean documentation.
Colorado mountain markets deliver the first two by default. We help with the third and the fourth.
If you are considering a Colorado short-term rental as a tax strategy and you want an operating partner who understands what your CPA is trying to accomplish, we should talk. We manage a portfolio of mountain properties across the Pikes Peak region and the Front Range foothills, and we work with investor-owners who care as much about the tax outcome as the revenue.
Evergreen Escapes is a boutique short-term rental co-hosting company serving Colorado mountain markets across Park, Teller, Clear Creek, Jefferson, El Paso, and Douglas counties. We are not tax professionals and nothing in this article constitutes tax advice.

Comments